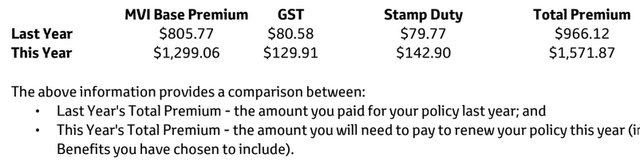
Wondering how much car insurance in Australia will cost you? You’re not alone.
Finding the right coverage at a price that fits your budget can feel confusing and overwhelming. But knowing what affects your car insurance price and what you can expect to pay puts you in control. You’ll discover clear answers and smart tips to help you save money while protecting your vehicle.
Keep reading to find out exactly how much car insurance could cost you and how to make the best choice for your needs.
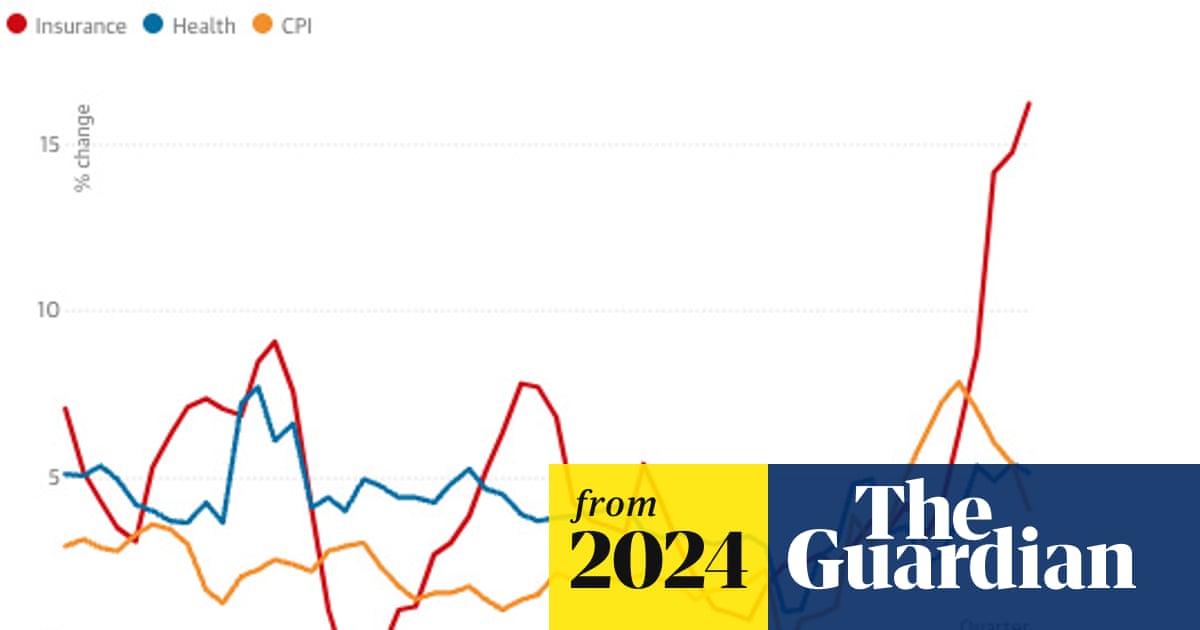
Credit: www.theguardian.com
Car Insurance Types
Car insurance in Australia comes in different types. Each type offers various levels of protection. Choosing the right type depends on your needs and budget. Understanding these types helps you make a better decision.
Comprehensive Coverage
Comprehensive coverage offers the highest level of protection. It covers damage to your car from accidents, theft, fire, and natural events. It also covers damage to other people’s property and injuries. This type is ideal for new or expensive cars.
Third Party Property Damage
This insurance covers damage you cause to other people’s property. It does not cover damage to your own vehicle. It is usually cheaper than comprehensive coverage. This type suits older cars or drivers on a tight budget.
Third Party Fire And Theft
This type covers third party property damage plus fire and theft of your car. It offers more protection than third party property damage alone. It is a middle ground between basic and full coverage. Good for cars that need extra security without high costs.

Credit: www.budgetdirect.com.au
Factors Affecting Premiums
Car insurance premiums in Australia vary based on several important factors. These factors help insurers assess the risk of covering a driver and their vehicle. Understanding them can help you see why prices differ so much between drivers and cars.
Each factor plays a role in how much you pay. Some relate to the driver’s profile, others to the vehicle, and some to how and where the car is used. These details shape the final insurance cost.
Driver Age And Experience
Young drivers often face higher premiums. Insurers see them as higher risk due to less driving experience. Older, more experienced drivers usually get lower rates. Safe driving records also reduce costs.
Vehicle Make And Model
Expensive or powerful cars cost more to insure. Sports cars and luxury vehicles carry higher premiums. Cars with strong safety ratings and lower repair costs have cheaper insurance. The model’s theft rate also affects the price.
Location And Usage
Where you live impacts your premium. Urban areas often have higher rates due to more accidents and thefts. Rural areas tend to have lower costs. How often and why you use your car also matters. Frequent driving increases risk and premiums.
Claims History
Drivers with past claims may pay more. Frequent claims suggest higher risk to insurers. A clean claims record usually leads to discounts. Being honest about your history helps get accurate quotes.
Average Insurance Costs
Understanding the average cost of car insurance in Australia helps you budget wisely and avoid surprises. Insurance prices vary widely depending on where you live, the type of vehicle you drive, and your personal driving history. Let’s break down these factors so you can get a clearer picture of what to expect.
By State And Territory
Insurance costs differ significantly across Australian states and territories. For example, drivers in New South Wales often pay higher premiums due to denser traffic and higher accident rates.
On the other hand, Tasmania generally offers cheaper insurance because of its lower traffic volume and fewer claims. Here’s a quick overview of average annual premiums by location:
| State/Territory | Average Annual Cost (AUD) |
|---|---|
| New South Wales | $1,200 |
| Victoria | $1,100 |
| Queensland | $1,000 |
| Western Australia | $950 |
| Tasmania | $850 |
Have you checked how your state stacks up? This difference alone can affect your choice of insurer.
By Vehicle Type
The kind of car you drive plays a huge role in insurance pricing. Sports cars and luxury vehicles usually cost more to insure because repairs and theft risk are higher.
On the flip side, smaller, older cars often attract lower premiums. Here’s a simple breakdown:
- Sports Cars:$1,500 – $2,500 per year
- Sedans and Hatchbacks:$900 – $1,300 per year
- Utes and SUVs:$1,000 – $1,400 per year
Think about your vehicle choice carefully—does the thrill of a sports car outweigh the extra insurance cost?
By Driver Profile
Your personal driving record and experience shape your insurance premium more than you might expect. New drivers or those with past claims typically face higher rates.
Safe drivers with clean histories often qualify for discounts and lower premiums. Age and gender can also influence costs, with younger drivers usually paying the most.
- Young Drivers (Under 25):$1,800 – $3,000 annually
- Experienced Drivers (25-65):$900 – $1,200 annually
- Senior Drivers (65+):$1,000 – $1,400 annually
Could improving your driving record save you hundreds? It’s worth considering if you want lower premiums.
Ways To Lower Premiums
Car insurance premiums in Australia can be high, but there are simple ways to lower them. Small changes can save you money every year. Understanding these options helps you choose the best approach for your needs.
No Claim Bonuses
No Claim Bonuses reward drivers who do not make claims. The longer you drive without a claim, the bigger your discount. This bonus can reduce premiums by up to 50%. It encourages safe driving and careful handling of your car.
Choosing Higher Excess
Excess is the amount you pay after a claim. Choosing a higher excess lowers your premium. It means you pay more out-of-pocket if an accident happens. This option suits those who want lower regular payments and can cover higher costs if needed.
Bundling Policies
Bundling means buying car insurance with other policies, like home or travel insurance. Insurers often offer discounts for bundled policies. It saves money and makes managing insurance easier. Check if your insurer provides bundle deals to reduce premiums.
Safe Driving Discounts
Safe Driving Discounts reward careful and responsible drivers. Some insurers track driving habits with devices or apps. Good scores can lead to lower premiums. Avoiding accidents, speeding, and harsh braking improve your chances of discounts.
Comparing Insurance Providers
Comparing insurance providers is essential for finding the right car insurance in Australia. Different companies offer various benefits, coverage options, and prices. Choosing the best provider helps you save money and get the protection you need.
Key Features To Consider
Look for important features like coverage limits, excess amounts, and policy inclusions. Check if the insurer offers roadside assistance or rental car coverage. Discounts for safe driving or multi-policy bundles can reduce costs. Understand what each policy covers before deciding.
Online Comparison Tools
Use online tools to compare multiple insurance quotes quickly. These tools show prices, features, and benefits side by side. Enter your details once and get offers from various companies. It saves time and helps spot the best deals easily.
Customer Reviews And Ratings
Read reviews to learn about other customers’ experiences. Pay attention to claims handling, customer service, and reliability. Higher ratings usually mean better satisfaction and fewer problems. Reviews give real insights beyond just price and features.
Legal Requirements And Coverage
Understanding the legal requirements and coverage for car insurance in Australia is essential. Each driver must have at least the minimum insurance to stay compliant with the law. This ensures protection for all road users.
Car insurance covers different risks, and choosing the right coverage depends on personal needs and budget. Knowing what is compulsory and what extras are available can save money and provide peace of mind.
Compulsory Third Party Insurance
Compulsory Third Party (CTP) insurance is mandatory for all registered vehicles in Australia. It covers injuries caused to other people in an accident. This insurance does not cover damage to vehicles or property.
Each state and territory has its own CTP scheme and rules. The cost varies depending on where you live and your vehicle type. Without CTP insurance, you cannot legally drive or register a car.
Optional Extras And Add-ons
Optional extras offer additional protection beyond CTP insurance. These can cover damage to your car, theft, or fire. You can choose from different types of policies:
- Third Party Property Damage – covers damage to others’ property.
- Comprehensive – covers damage to your vehicle and others.
- Fire and Theft – covers your car if stolen or damaged by fire.
Add-ons include benefits like roadside assistance and rental car coverage. These extras increase the insurance cost but offer more security. It is important to compare options to find the best fit for your needs.
Impact Of Recent Trends
Recent trends shape the cost and structure of car insurance in Australia. These changes influence how insurers set premiums and how drivers pay for coverage. Understanding these trends helps drivers make smart choices and save money.
Telematics And Usage-based Insurance
Telematics technology tracks driving habits through a device or app. It measures speed, braking, and distance driven. Insurers use this data to offer usage-based insurance (UBI).
UBI rewards safe drivers with lower premiums. It creates a fairer pricing system based on actual risk. Drivers who drive less or carefully pay less for insurance. This trend is growing fast in Australia.
Effects Of Covid-19 On Premiums
COVID-19 reduced driving due to lockdowns and work-from-home rules. Fewer cars on roads led to fewer accidents. Insurers responded by lowering premiums or offering rebates.
Some drivers saw reduced costs in 2020 and 2021. As travel returned, premiums started rising again. The pandemic showed how driving habits affect insurance prices quickly.
Credit: www.cars24.com.au
Frequently Asked Questions
What Factors Affect Car Insurance Cost In Australia?
Car insurance costs in Australia are influenced by factors like age, driving history, and car model. Location also plays a crucial role. Urban areas may see higher premiums due to traffic and theft risks. Additionally, the level of coverage chosen significantly impacts the overall cost of insurance.
Is Car Insurance Mandatory In Australia?
Yes, car insurance is mandatory in Australia. Compulsory Third Party (CTP) insurance is required for all registered vehicles. It covers injury to others in an accident. However, it doesn’t cover damage to your vehicle or property. For broader protection, Australians often opt for additional insurance types like comprehensive coverage.
How Can I Reduce My Car Insurance Premium?
To reduce your car insurance premium, consider increasing your excess and maintaining a clean driving record. Bundling policies, such as car and home insurance, can also offer discounts. Installing safety devices in your car and choosing a higher deductible are additional strategies to lower your premium costs.
Does Car Insurance Cover Natural Disasters In Australia?
Comprehensive car insurance often covers natural disasters in Australia, such as floods, storms, and bushfires. However, it’s crucial to verify specific policy details, as coverage can vary. Always read the terms carefully to ensure you’re protected against the natural events most common in your area.
Conclusion
Car insurance costs in Australia vary by many factors. Age, car type, and driving history affect the price. Choosing the right coverage helps protect your money. Comparing quotes saves you from paying too much. Knowing what influences your premium gives you control.
Always read the policy details before signing. Stay safe and insured on every trip. Car insurance is an important part of driving. Keep these points in mind to find a good deal.