Are you wondering how much car insurance in Michigan will cost you? Finding the right coverage without overpaying can feel confusing.
But knowing what affects your rates and what to expect can save you money and stress. You’ll get clear answers about Michigan car insurance costs and tips to get the best deal for your needs. Keep reading—you might be closer to affordable coverage than you think.

Credit: www.michiganautolaw.com
Michigan Car Insurance Basics
Understanding Michigan car insurance basics helps drivers save money. Insurance costs vary by many factors. Knowing state rules and insurance types prepares you to choose the right coverage.
State Requirements
Michigan law requires all drivers to have car insurance. The minimum coverage includes:
- Bodily injury liability
- Property damage liability
- Personal injury protection (PIP)
- Residual bodily injury liability
These coverages protect drivers in case of accidents. The state sets minimum amounts for each type. Insurance companies must follow these rules.
No-fault Insurance Explained
Michigan uses a no-fault insurance system. This means your insurance pays your medical bills, regardless of fault. It speeds up claims and reduces lawsuits.
Drivers must buy personal injury protection (PIP). It covers:
- Medical expenses
- Lost wages
- Rehabilitation costs
No-fault insurance helps people get care quickly. It also lowers court cases for car accidents.

Credit: insurify.com
Factors Affecting Insurance Rates
Understanding how much car insurance costs in Michigan involves several factors. Each factor plays a significant role in determining your insurance rates. Knowing these can help you manage costs effectively.
Driver Age And Experience
Young drivers often pay higher premiums. This is due to their lack of experience. Insurance companies see them as higher risk. Older drivers usually have more experience. They tend to enjoy lower rates. A clean driving history can further reduce costs.
Vehicle Type And Usage
The type of car you drive affects your insurance. Sports cars often have higher rates. They are seen as riskier to insure. Using your vehicle for business can also impact rates. Higher mileage increases risk, leading to higher costs.
Location And Zip Code
Where you live in Michigan affects your insurance rates. Urban areas tend to have higher rates. This is due to more traffic and potential accidents. Rural areas might see lower premiums. Your ZIP code can influence theft and vandalism risks.
Driving Record Impact
Your driving record is crucial in determining your rates. Accidents and traffic violations increase premiums. A clean driving record can lead to discounts. Safe drivers are rewarded with lower insurance costs.
Average Car Insurance Costs In Michigan
Understanding the average car insurance costs in Michigan helps drivers plan their budgets. Insurance rates vary based on many factors like age, driving history, and coverage level. Knowing typical premiums helps compare options and find suitable plans.
Typical Annual Premiums
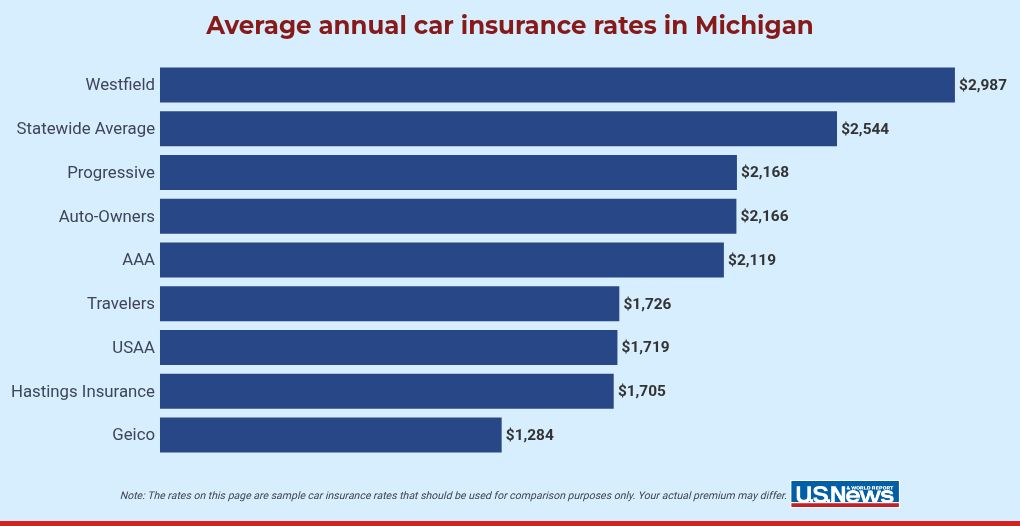
The average annual car insurance premium in Michigan is around $2,500. This amount can change depending on your location and driving record. Urban areas often have higher rates than rural ones. Young drivers usually pay more, while experienced drivers get lower rates. Basic coverage costs less, but full coverage raises the premium.
Comparison With National Averages
Michigan’s car insurance rates are higher than the national average. The U.S. average annual premium is about $1,700, which is much lower. Several reasons raise Michigan’s costs, including its no-fault insurance system. This system requires personal injury protection, increasing premiums. Despite higher costs, Michigan offers strong coverage benefits.

Credit: insurify.com
Additional Coverage Options
Understanding the additional coverage options in Michigan car insurance can make a big difference in how protected you feel on the road. These coverages go beyond the basic requirements and offer extra layers of security. They also influence your overall premium, so knowing what each one covers helps you decide what you really need.
Personal Injury Protection (pip)
Personal Injury Protection, or PIP, is a unique coverage required in Michigan. It pays for medical expenses, lost wages, and other related costs if you’re injured in an accident, regardless of who is at fault.
Think about it: if you or your passengers get hurt, PIP can cover hospital bills and even help with rehabilitation. Without it, those costs could come straight out of your pocket, which might be financially overwhelming.
Property Protection
Property Protection helps cover damage you cause to someone else’s property, such as fences, buildings, or utility poles. This coverage is especially important in Michigan, where property damage claims can be frequent due to weather-related incidents.
Imagine accidentally hitting a neighbor’s fence during a winter snowstorm. Property Protection steps in to handle the repair costs, so you don’t have to pay for the damages yourself.
Uninsured Motorist Coverage
Uninsured Motorist Coverage protects you if you’re involved in an accident with a driver who doesn’t have insurance. It also covers situations where the at-fault driver can’t be identified, like a hit-and-run.
Given Michigan’s high rates of uninsured drivers, this coverage is crucial. It ensures you’re not stuck paying medical bills or repair costs when the other party can’t cover them.
Ways To Lower Your Premium
Lowering your car insurance premium in Michigan is more achievable than you might think. Small changes in your profile, coverage choices, and taking advantage of available discounts can significantly reduce what you pay. Let’s look at practical ways you can start saving today.
Discounts And Savings
Insurance companies offer various discounts that can cut your premium. Are you a safe driver? Many providers reward clean driving records with lower rates.
- Multi-policy discounts – bundling auto with home or renters insurance often saves money.
- Good student discounts – if you or a family member is a student with strong grades, ask about this.
- Low mileage discounts – driving less can mean paying less.
- Vehicle safety features – cars with anti-theft devices or advanced safety tech often qualify for discounts.
Have you checked with your insurer about all the discounts you might qualify for? Sometimes just asking can open new savings.
Improving Your Driving Profile
Your driving habits and history directly affect your premium. Avoiding accidents and traffic violations is crucial, but there’s more you can do.
- Consider taking a defensive driving course to demonstrate commitment to safe driving.
- Keep your credit score healthy, as some insurers use it to determine risk.
- Use telematics programs that monitor your driving; careful drivers often receive lower rates.
Think about your recent driving habits—could you make small changes that show insurers you’re less risky? It’s a powerful way to reduce costs.
Choosing The Right Coverage
Having the right insurance coverage means paying only for what you truly need. Over-insuring can unnecessarily raise your premium.
- Review your coverage limits and deductibles regularly to find a balance between protection and cost.
- Consider dropping coverage on older vehicles that are worth less than the insurance cost.
- Look for policies tailored to Michigan’s unique no-fault system to avoid paying extra for redundant coverage.
Ask yourself: does each part of your policy match your current needs and budget? Adjusting coverage can lead to immediate savings.
Impact Of Michigan’s Auto Insurance Reform
Michigan’s auto insurance reform has reshaped the way drivers pay for coverage across the state. These changes aim to balance affordable insurance with adequate protection for all drivers. Understanding the impact helps you make better choices about your own car insurance costs.
Recent Legislative Changes
In 2020, Michigan introduced a significant overhaul to its no-fault auto insurance system. The reform gave drivers more options to customize their Personal Injury Protection (PIP) coverage. You can now choose from different levels of medical coverage instead of the unlimited lifetime benefits that were mandatory before.
The law also adjusted rates based on factors like driving history and vehicle usage more than before. Insurers gained more flexibility to offer discounts and tailor policies. This shift means your premiums can better reflect your personal risk and coverage preferences.
How Reforms Affect Costs
The reform’s goal was to reduce the state’s notoriously high insurance rates. Some drivers have seen their premiums drop, especially those who opted for lower PIP coverage or have clean driving records. However, if you choose to keep unlimited medical benefits, your rates might not change much.
Many drivers report saving hundreds of dollars annually by selecting coverage levels that fit their needs. But it’s important to review your choices carefully—cutting coverage too much could lead to higher out-of-pocket costs after an accident. How much coverage do you really need to feel secure without overpaying?
Shopping For Michigan Car Insurance
Shopping for car insurance in Michigan requires careful thought. Prices vary widely by company and coverage. Smart shoppers compare options to find the best deal. Knowing where to start saves time and money. Understanding key players and tools helps too.
Comparing Quotes
Compare quotes from multiple insurers before choosing. Each company calculates rates differently. Factors include your driving record, car model, and location. Collect several quotes to see price differences clearly. Check coverage details, not just the price. Sometimes a cheaper policy has less protection.
Top Insurers In Michigan
Many insurers serve Michigan drivers. Some have strong reputations and good customer service. Popular companies include:
- State Farm
- Allstate
- Geico
- Progressive
- Auto-Owners Insurance
These insurers offer a range of plans and discounts. Choose one that fits your budget and needs.
Using Online Tools
Online tools make shopping easier. Use comparison websites to view many quotes at once. Input basic information to get estimates fast. Many sites highlight discounts you might qualify for. Some insurers offer direct online quotes too. Use these tools to save effort and find good prices.
Frequently Asked Questions
How Much Is Average Car Insurance In Michigan?
The average car insurance cost in Michigan is around $2,000 to $2,500 annually. This rate is higher than the national average due to Michigan’s no-fault insurance laws and mandatory personal injury protection coverage.
Why Is Michigan Car Insurance So Expensive?
Michigan’s car insurance is costly because of its no-fault system, high medical benefit coverage, and rising claims costs. These factors drive premiums higher than in many other states.
Can I Lower My Michigan Car Insurance Premium?
Yes, you can lower premiums by comparing quotes, increasing deductibles, bundling policies, and maintaining a clean driving record. Discounts for safe driving and vehicle safety features also help reduce costs.
What Factors Affect Michigan Car Insurance Rates?
Factors include your driving history, age, vehicle type, coverage limits, location, and credit score. Michigan’s insurance rules and required personal injury protection also influence rates significantly.
Conclusion
Car insurance costs in Michigan vary by many factors. Your age, driving record, and car type affect your price. Comparing quotes helps find the best rate. Choosing the right coverage protects your finances. Understanding costs allows smarter decisions on insurance.
Keep your information updated to get accurate quotes. Stay safe on the road and save money. Insurance is important for peace of mind. Regularly review your policy to avoid surprises. This helps you manage expenses and risks well.